Artificial intelligence has become one of the most powerful forces shaping the stock market, driving investment into semiconductor manufacturers, cloud-computing platforms, and data-center infrastructure. But as spending accelerates and financing costs remain elevated, a critical question is emerging on Wall Street: are investors paying too much for the promise of AI before its long-term financial benefits are fully established?
Recent comments from Citadel founder Ken Griffin have brought this debate into sharper focus. At a financial-markets conference, Griffin discussed the possibility that enthusiasm for advanced AI models could resemble earlier speculative episodes, while also recognizing the technology’s potential to transform businesses. His remarks highlight a distinction investors must understand: a technology can fundamentally change the economy while some of the stocks associated with it still become overpriced.
For investors, the issue is not simply whether AI will succeed. It is whether the companies receiving the largest investments can generate sufficient earnings and cash flow to justify their valuations.
Why Investors Are Questioning the AI Rally
The AI investment boom has attracted enormous amounts of capital. Major technology companies are expanding computing capacity, purchasing advanced processors, and building facilities designed to support increasingly sophisticated AI models. Investors have rewarded businesses positioned to benefit from this spending, helping make AI a central theme in equity-market performance.
However, the scale of investment is increasing scrutiny of the assumptions behind current share prices.
According to The Wall Street Journal‘s October 21 coverage of Griffin’s comments, companies are becoming more conscious of the costs of advanced AI tools and are evaluating whether those expenses produce meaningful productivity improvements. That shift matters because strong demand for AI services does not automatically translate into attractive returns for every company supplying them.
The investment case depends on several factors: how quickly businesses adopt AI, whether customers are willing to pay for increasingly powerful services, how much competition reduces pricing power, and how efficiently providers manage the cost of computing.
If adoption and monetization exceed expectations, leading AI businesses could continue expanding profitably. If revenue growth falls short of ambitious forecasts, however, investors may reassess valuations even when underlying demand remains healthy.
The historical comparison with the dot-com era is therefore relevant, although it should not be taken too far. The internet ultimately transformed commerce and communication, but many internet-related companies failed because their valuations, funding structures, or business models were unsustainable. AI could similarly produce enormous economic benefits without rewarding every company associated with it.
High Treasury Yields Add Pressure to Technology Valuations
Interest rates are another important part of the equation. When long-term government bond yields rise, investors have a more attractive alternative to equities, while companies face higher financing costs.
The Federal Reserve’s daily interest-rate data showed the U.S. 10-year Treasury yield at approximately 5.15% on October 19, 2026. That level provides an important benchmark for assessing the prices investors are willing to pay for future corporate earnings.
High-growth technology companies can be particularly sensitive to changes in interest rates because a substantial portion of their expected value may depend on profits projected years into the future. In valuation models, those future cash flows are discounted to reflect the time value of money and investment risk. When discount rates increase, the present value of distant earnings generally declines.
This does not mean every technology stock must fall when yields rise. Companies with strong current earnings, durable competitive advantages, and consistent free cash flow may prove more resilient than businesses relying on distant growth expectations.
Nevertheless, elevated yields can make highly valued shares more vulnerable to disappointing results. A company does not necessarily need to report declining revenue to experience a sharp valuation adjustment; it may be enough for growth to fall short of what investors had already priced in.
For market participants, the relationship between Treasury yields, earnings expectations, and technology-stock valuations deserves close attention during the current earnings season.
The Data-Center Spending Challenge
The AI debate extends beyond software and semiconductor companies. It also concerns the enormous physical infrastructure required to train and operate advanced models.
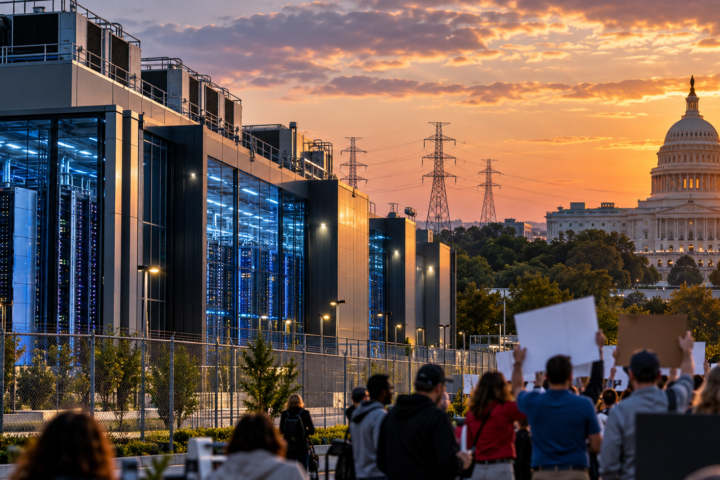
Data centers require computing equipment, electricity, cooling systems, land, and reliable network connections. These facilities can create opportunities for semiconductor suppliers, utilities, electrical-equipment manufacturers, construction companies, and energy infrastructure providers. Yet they also require substantial upfront capital and may take years to deliver their expected financial returns.
In an October 21 report, MarketWatch highlighted BlackRock CEO Larry Fink’s warning that resistance to data-center construction could contribute to inflationary pressures. Fink argued that technology-related capital expenditure has become central to the U.S. economy and emphasized the importance of expanding infrastructure to support AI and cloud computing.
The argument illustrates a difficult economic trade-off. Rapid construction can increase demand for electricity, equipment, skilled workers, and building materials. If supply cannot keep pace, costs may rise. At the same time, delays or cancellations could prevent companies from expanding computing capacity quickly enough to meet demand.
For investors, the distinction between infrastructure demand and infrastructure profitability is crucial. A growing need for computing power does not guarantee that every project will earn an adequate return.
Investors should examine project financing, expected utilization, customer commitments, energy availability, depreciation costs, and the timing of anticipated cash flows. Companies taking on substantial debt to fund facilities may be more exposed to refinancing costs and delays than businesses with stronger balance sheets.
The Financial Times has also reported on challenges facing the U.S. data-center expansion, including project delays, local opposition, financing difficulties, and questions about the feasibility of some proposed developments. These constraints reinforce the need to assess individual projects rather than treating the entire AI infrastructure market as a single investment opportunity.
Why the AI Bubble Debate Is More Complicated Than It Appears
Calling the entire AI sector a bubble may be as misleading as assuming that every AI-related investment will succeed.
AI has the potential to improve productivity, automate repetitive tasks, support research, and help businesses develop new products. Companies that translate these capabilities into measurable cost savings or additional revenue could establish durable competitive advantages.
The difficulty is identifying which businesses will capture the economic value.
Chipmakers may benefit from strong demand for advanced processors, but competition, customer concentration, product cycles, and capital spending by large technology customers can influence future growth. Cloud providers may gain new customers while simultaneously facing rising infrastructure costs. AI application companies may attract users but struggle to convert adoption into recurring revenue or sustainable margins.
The market may therefore become increasingly selective. Businesses with demonstrable demand, pricing power, strong balance sheets, and disciplined spending could outperform companies whose prospects depend primarily on optimistic forecasts.
Another factor is the concentration of market returns. When a relatively small group of large technology companies drives a substantial share of index performance, disappointment among those companies can affect broader benchmarks. Investors should understand their exposure to overlapping AI-related businesses rather than assuming a diversified fund eliminates all concentration risk.
The central question is not whether AI represents a major technological shift. It is how much of that future success is already reflected in today’s prices.
What Investors Should Watch Next
Several developments could help determine whether current AI valuations remain sustainable.
1. Earnings quality and cash flow
Revenue growth is important, but investors should also assess operating margins, free cash flow, and the cost of delivering AI services. Growing sales accompanied by sharply rising expenses may offer a weaker investment case than growth supported by improving profitability.
2. Capital expenditure and returns
Major technology companies’ quarterly reports can reveal whether spending plans are increasing, stabilizing, or being revised. Investors should compare capital expenditure with revenue growth and evidence that new infrastructure is generating productive returns.
3. Treasury yields and inflation
Persistent inflation or higher long-term yields could place additional pressure on expensive growth stocks. Conversely, a sustained decline in yields could ease valuation pressure, although it would not eliminate company-specific risks.
4. Financing conditions
Monitor borrowing costs, debt maturities, and access to new capital among data-center developers and AI infrastructure providers. Projects that depend on continuous refinancing may be more vulnerable if credit conditions deteriorate.
5. Competition and customer demand
Investors should watch for changes in AI pricing, customer retention, model performance, and the emergence of competing technologies. Strong adoption is most valuable when companies can retain customers and earn attractive margins.
Key Investment Insight: Focus on Fundamentals, Not the Hype
The current debate does not require investors to choose between embracing AI and avoiding the sector entirely. A more useful approach is to distinguish between technological potential and the price being paid for that potential.
Investors evaluating AI-related companies should compare valuations with earnings growth, free cash flow, balance-sheet strength, and realistic estimates of future demand. They should also consider how higher interest rates could affect financing costs and the present value of expected returns.
Diversification can help reduce the risk of relying too heavily on a single theme, while periodic portfolio reviews can identify excessive exposure to companies whose prices depend on similar assumptions. No valuation metric or market signal can reliably predict the exact timing of a correction, so investment decisions should account for uncertainty rather than depend on a single forecast.
Ultimately, the most attractive opportunities may emerge among businesses that turn AI investment into measurable economic value—not necessarily those receiving the most attention.
The AI revolution may continue reshaping the global economy, but that does not make every AI stock a sound investment at every price. Ken Griffin’s comments, scrutiny of data-center spending, and elevated Treasury yields underscore the importance of evaluating both growth opportunities and financial risks.
For investors, the next phase of the AI market may depend less on ambitious announcements and more on evidence of sustainable earnings, productive capital expenditure, and disciplined financing.
Stay informed with Stockmarket-news for daily investor-focused reporting, market analysis, and insights into the trends shaping U.S. and Canadian financial markets.