Oil markets entered a new phase of uncertainty Monday as Brent crude pushed above $108 a barrel following attacks on Saudi Arabia’s critical East-West pipeline and continued disruption around the Strait of Hormuz. For investors, the move is no longer simply another geopolitical spike in energy prices: it is becoming a broader market story involving inflation, interest rates, bond yields, corporate margins and the outlook for the U.S. economy.
Reuters reported on September 14 that Brent crude climbed to approximately $108.04 a barrel while U.S. West Texas Intermediate (WTI) reached $103.54, with both benchmarks rising more than 3%. The latest move comes after oil had already surged roughly 9% the previous week, underscoring how quickly supply concerns are being priced into global energy markets.
Saudi Pipeline Attack Raises the Stakes
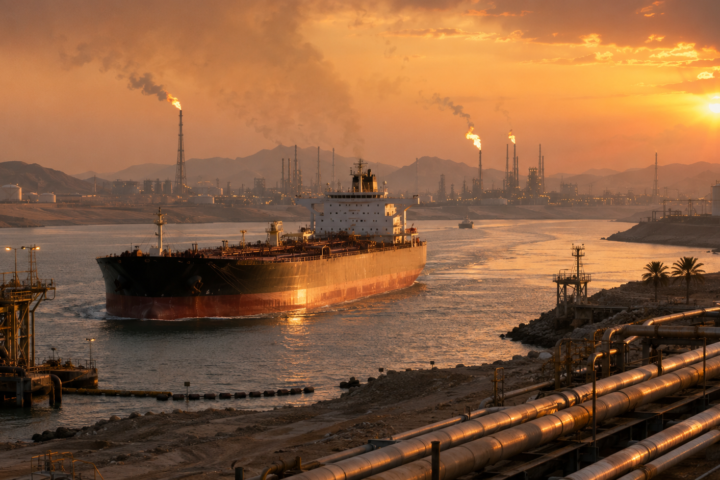
The immediate catalyst is the temporary shutdown of Saudi Arabia’s East-West oil pipeline following drone attacks. The approximately 1,200-kilometer pipeline is a crucial alternative route that allows Saudi crude to bypass the Strait of Hormuz and reach the Red Sea port of Yanbu.
According to Reuters, the disruption threatens as much as 4% of global oil supply if the pipeline cannot be restored quickly. Saudi Arabia has only several days of export-ready crude available at Yanbu, meaning a prolonged outage could put additional pressure on already-constrained global inventories.
The timing is particularly significant. Oil markets were already dealing with disruptions to shipments through the Strait of Hormuz and the Bab el-Mandeb, two strategically important maritime chokepoints. New attacks on vessels and continued regional instability have made traders increasingly concerned that additional supply losses could occur before existing disruptions are resolved.
Reuters’ latest analysis describes the current environment as a prolonged challenge for oil markets, with global inventories having fallen substantially since the conflict began and refined-fuel shipments severely disrupted.
Why the Strait of Hormuz Matters
The Strait of Hormuz remains one of the world’s most important energy chokepoints. Any prolonged reduction in tanker traffic through the waterway can have an outsized effect on prices because alternative transportation routes cannot immediately replace the enormous volumes normally moving through the region.
That makes the Saudi East-West pipeline particularly important. It was designed in part to provide an alternative route around Hormuz. The fact that infrastructure intended to reduce Saudi Arabia’s exposure to the chokepoint has itself come under attack demonstrates how difficult it could be for producers to fully insulate their exports from the regional conflict.
Reuters Breakingviews also noted Monday that proposals to bypass Hormuz through additional pipelines could take years to implement, highlighting the limits of infrastructure-based solutions in the near term.
For investors, the key question is therefore not simply whether oil can reach $110. It is whether the market can maintain sufficient physical supply if multiple transportation routes remain impaired simultaneously.
The Inflation Problem Is Back
Oil’s rally is arriving at an especially sensitive time for the U.S. economy.
Higher crude prices eventually feed into gasoline, diesel, transportation and production costs. If elevated energy prices persist, they can make it more difficult for inflation to return to the Federal Reserve’s 2% target.
That is already influencing interest-rate expectations. Reuters reported Monday that Goldman Sachs, JPMorgan, HSBC and Deutsche Bank were among major institutions expecting the Federal Reserve to raise rates by 25 basis points at its September 15-16 meeting.
Reuters also reported that markets were assigning a high probability to a rate increase, with oil prices adding another layer of inflation pressure following already-firm U.S. inflation data.
This creates an unusual feedback loop for investors:
Geopolitical escalation → higher oil prices → higher inflation expectations → higher interest-rate expectations → higher bond yields → pressure on equity valuations.
That dynamic could be particularly important for growth stocks whose valuations depend heavily on expectations for future earnings.
Bond Yields Add Another Warning Signal
The oil shock is already showing up outside commodities markets.
Reuters reported that the U.S. 10-year Treasury yield approached 5%, reaching roughly 4.99% before retreating slightly. Rising oil prices and inflation concerns are among the factors contributing to upward pressure on yields.
A sustained move above 5% would represent a meaningful development for equity investors because higher Treasury yields increase the relative attractiveness of bonds and raise the discount rate applied to future corporate earnings.
That could leave investors facing pressure from both sides: energy-intensive businesses could see costs increase while high-growth companies could face valuation compression from higher interest rates.
Which Investors Could Benefit?
The clearest potential beneficiaries are companies with direct exposure to higher oil and natural-gas prices.
U.S. and Canadian upstream producers could benefit if higher crude prices translate into stronger realized prices and expanding cash flows. Oilfield-services companies could also attract attention if producers increase spending to capitalize on a more favorable commodity-price environment.
The situation may also reinforce the strategic value of North American energy infrastructure.
Companies involved in pipelines, storage, LNG exports, drilling equipment and other energy infrastructure could become increasingly important as governments and businesses seek supply security outside vulnerable Middle Eastern shipping routes.
However, investors should distinguish between higher commodity prices and higher corporate profits. Producers with high operating costs, heavy capital requirements or significant debt may not benefit as much as financially stronger companies.
Who Could Face Pressure?
The other side of the oil rally is potentially more challenging.
Airlines, trucking companies, shipping firms, chemical manufacturers and other energy-intensive businesses can face higher operating costs when crude and refined-product prices rise.
Consumer-facing companies could also encounter margin pressure if fuel and transportation expenses increase faster than they can raise prices.
For equity investors, this means that an oil shock can produce significant sector rotation rather than simply lifting the entire energy sector.
Energy stocks may outperform while transportation, consumer discretionary and other fuel-sensitive industries come under pressure.
The Bigger Risk: A Prolonged Supply Shock
The most important variable to watch is duration.
A short-lived pipeline shutdown could produce a sharp but temporary oil-price spike. If Saudi Arabia restores the pipeline quickly and shipping conditions improve, some of the geopolitical premium could unwind.
A prolonged disruption would be considerably more consequential.
Reuters has reported that Saudi Arabia’s oil production had already fallen substantially from earlier levels, while global inventories have been depleted during the conflict.
That means the market has less room for another major supply shock.
Investors should therefore monitor several indicators closely:
- Brent crude: Whether prices establish a sustained position above $100.
- WTI: Whether U.S. crude follows Brent higher and maintains the $100 level.
- Saudi pipeline repairs: How quickly the East-West pipeline returns to normal operations.
- Strait of Hormuz traffic: Whether tanker movements recover or deteriorate further.
- U.S. Treasury yields: Whether the 10-year yield breaks decisively above 5%.
- Federal Reserve guidance: Whether policymakers signal additional rate increases.
- Gasoline and diesel prices: Evidence that the crude shock is spreading into consumer inflation.
- Energy-company earnings: Whether higher crude prices are translating into stronger free cash flow.
Key Investment Insight
For investors, the current oil rally should be viewed as both a commodity opportunity and a macroeconomic warning.
Energy producers with strong balance sheets and relatively low production costs may benefit from a prolonged period of elevated crude prices. North American energy infrastructure and oilfield services also deserve attention if companies and governments increase investment in supply security.
But chasing oil prices after a rapid geopolitical rally carries substantial risk. A diplomatic breakthrough, restoration of the Saudi pipeline or normalization of shipping through Hormuz could trigger a sharp reversal.
The broader portfolio implication may be even more important: oil above $100 is no longer an isolated commodities story. It is becoming a critical variable for inflation, monetary policy, Treasury yields and equity valuations.
Investors should focus less on predicting the exact next oil-price target and more on determining which companies have the strongest balance sheets, lowest costs and greatest ability to benefit—or withstand—an extended period of energy-market volatility.
What to Watch Next
The next several trading sessions could be decisive.
Markets will be watching whether Saudi Arabia can restore the East-West pipeline, whether regional attacks intensify, and whether diplomatic efforts surrounding the Strait of Hormuz resume. At the same time, the Federal Reserve’s September 15-16 meeting could determine how markets interpret the inflationary consequences of $100-plus oil.
For now, the message from the commodities market is clear: the global oil system has become increasingly vulnerable to another supply disruption.
For investors, that makes energy exposure, inflation protection and portfolio sensitivity to interest rates more important than they were just weeks ago.
Stay with Stockmarket-news for the latest market-moving developments, investor analysis and daily insights across commodities, equities, rates and the global economy.